Zero down is often possible
Many eligible buyers can purchase with no down payment when the loan and property meet VA and lender guidelines.
Kennewick · Pasco · Richland · West Richland
A clear, local guide for Veterans, active-duty service members, Guard and Reserve members, and surviving spouses. Learn how VA loans work, how to request a Certificate of Eligibility, and how Maltos Realty Group can help you buy or sell here.
Many eligible buyers can purchase with no down payment when the loan and property meet VA and lender guidelines.
VA-backed loans do not require private mortgage insurance, which can lower the monthly payment compared with many low-down conventional loans.
Most VA loans include a one-time funding fee. Disabled Veterans and some surviving spouses may be exempt.
Justin Maltos and the Maltos Realty Group team help Veterans buy and sell in the Tri-Cities. Your consultation is free.
How it works
A VA-backed home loan is a benefit earned through qualifying military service. A private lender makes the loan. The Department of Veterans Affairs guarantees a portion of it, which is why many buyers can put little or nothing down and skip monthly PMI.
This page is general information, not a loan offer, a pre-approval, or a guarantee of terms. Interest rates, eligibility, and closing costs depend on your service history, credit, income, the property, and the lender you choose. We can introduce you to lenders who regularly work with VA buyers in this market. Two options are listed in the pre-approval section below.
The basics
If you have remaining VA entitlement and the home meets VA and lender guidelines, a zero-down purchase is often possible. Some buyers still choose to bring money to closing. Your lender will confirm what applies to you.
Most borrowers pay a one-time VA funding fee, which can usually be financed into the loan or paid at closing. The amount varies based on the type of loan, whether you have used the benefit before, and any down payment.
You generally do not pay the funding fee if you receive VA compensation for a service-connected disability, if you are eligible for that compensation but receive retirement or active-duty pay instead, if you are a surviving spouse receiving Dependency and Indemnity Compensation, or if you meet certain other VA exemption rules, including some Purple Heart recipients on active duty. Ask your lender to confirm your status. Details are on va.gov.
A VA-approved appraiser gives an opinion of value and checks that the home meets VA minimum property requirements. In plain terms, the home should be safe, structurally sound, and sanitary, with basic living, sleeping, cooking, and bathroom space, plus utilities such as electricity, heat, and a safe water and sewer or septic system. A VA appraisal is not a full home inspection. We still recommend a thorough inspection.
Certificate of Eligibility
A Certificate of Eligibility is the VA document that shows a lender you qualify for the home loan benefit based on your service history or surviving-spouse status.
You can request a COE in any of these ways:
Veterans typically need a DD214 or other discharge papers. Minimum service requirements depend on when you served, and some discharges are reviewed case by case. If you are not sure whether you qualify, apply anyway. The VA reviews the record and issues or explains the result. We can walk you through the checklist in a free consultation. We cannot issue a COE ourselves.
Washington benefit
Washington state may reduce property taxes for Veterans with a qualifying service-connected disability who own and occupy the home as their primary residence and meet county income limits.
In general, the program can apply if you have a combined service-connected evaluation of 40 percent or higher, or if you receive VA compensation at the total-disability rate. Surviving spouses or partners may qualify in some cases. Income thresholds vary by county, and you apply through your county assessor, not through us. Benton County and Franklin County each have an assessor’s office that can confirm current rules. This is general information, not tax advice. For official details, see the Washington Department of Revenue.
The Tri-Cities
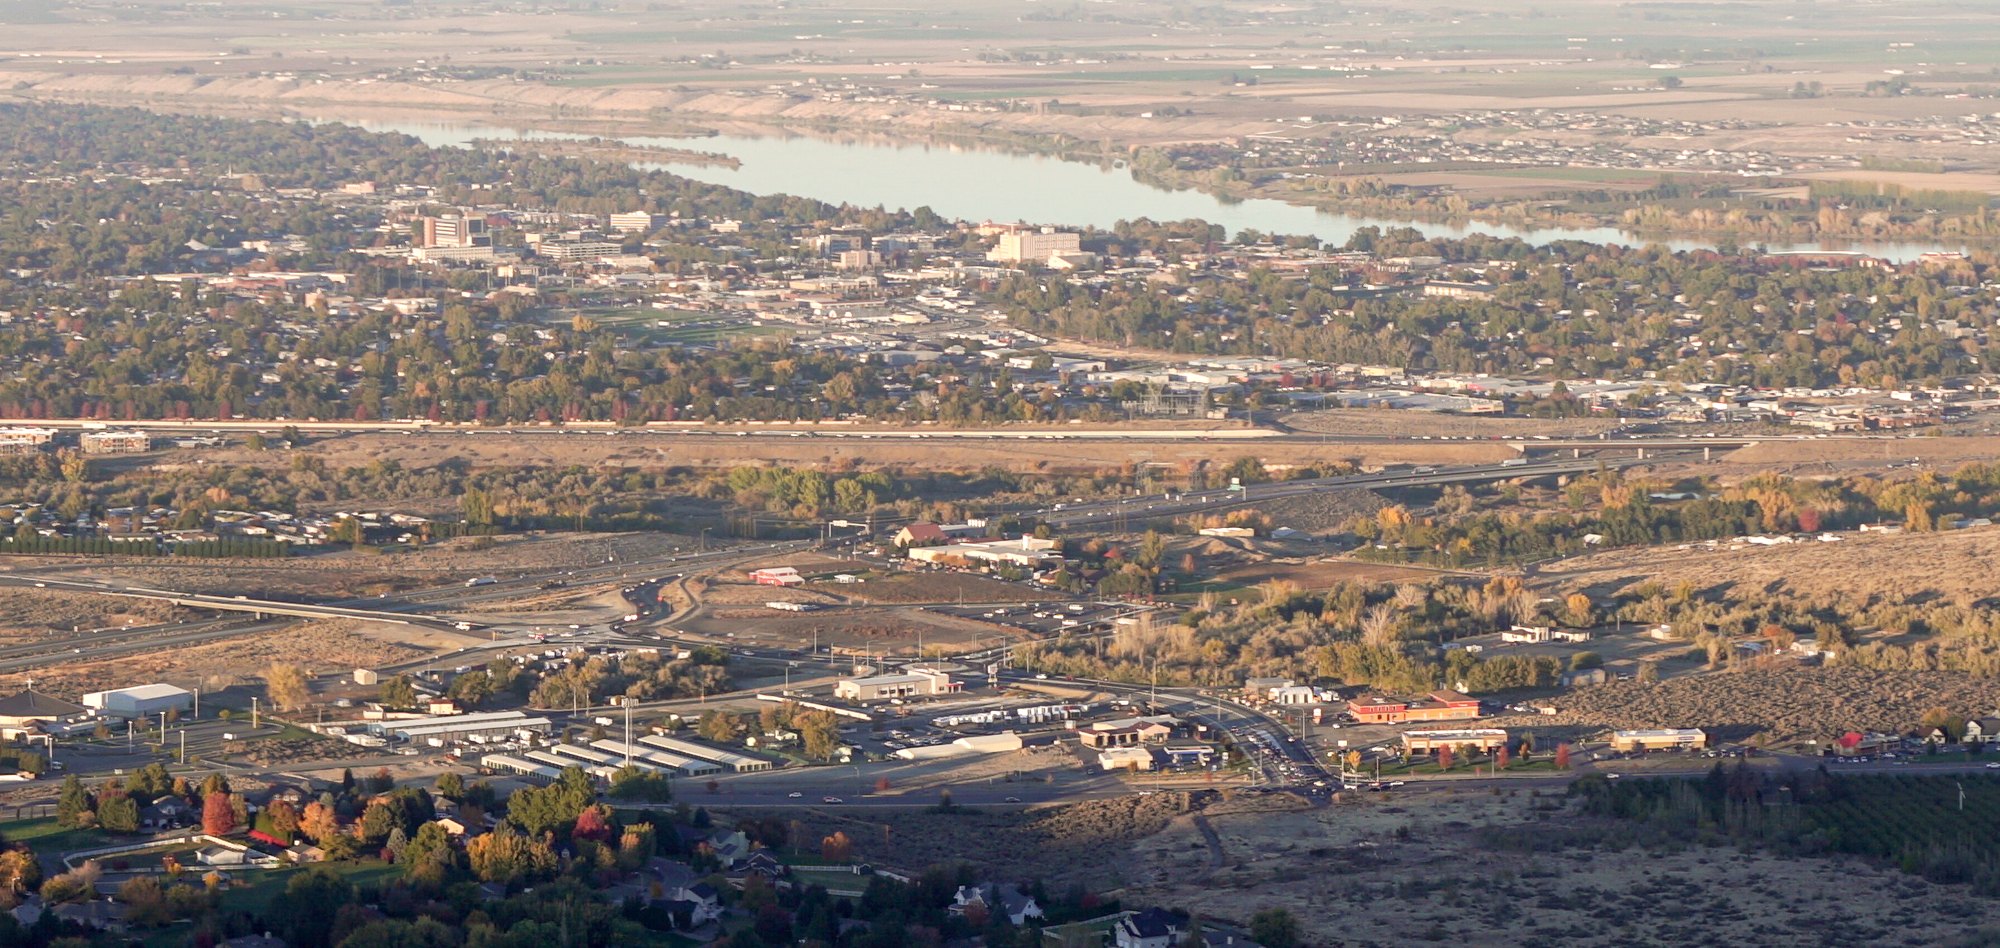
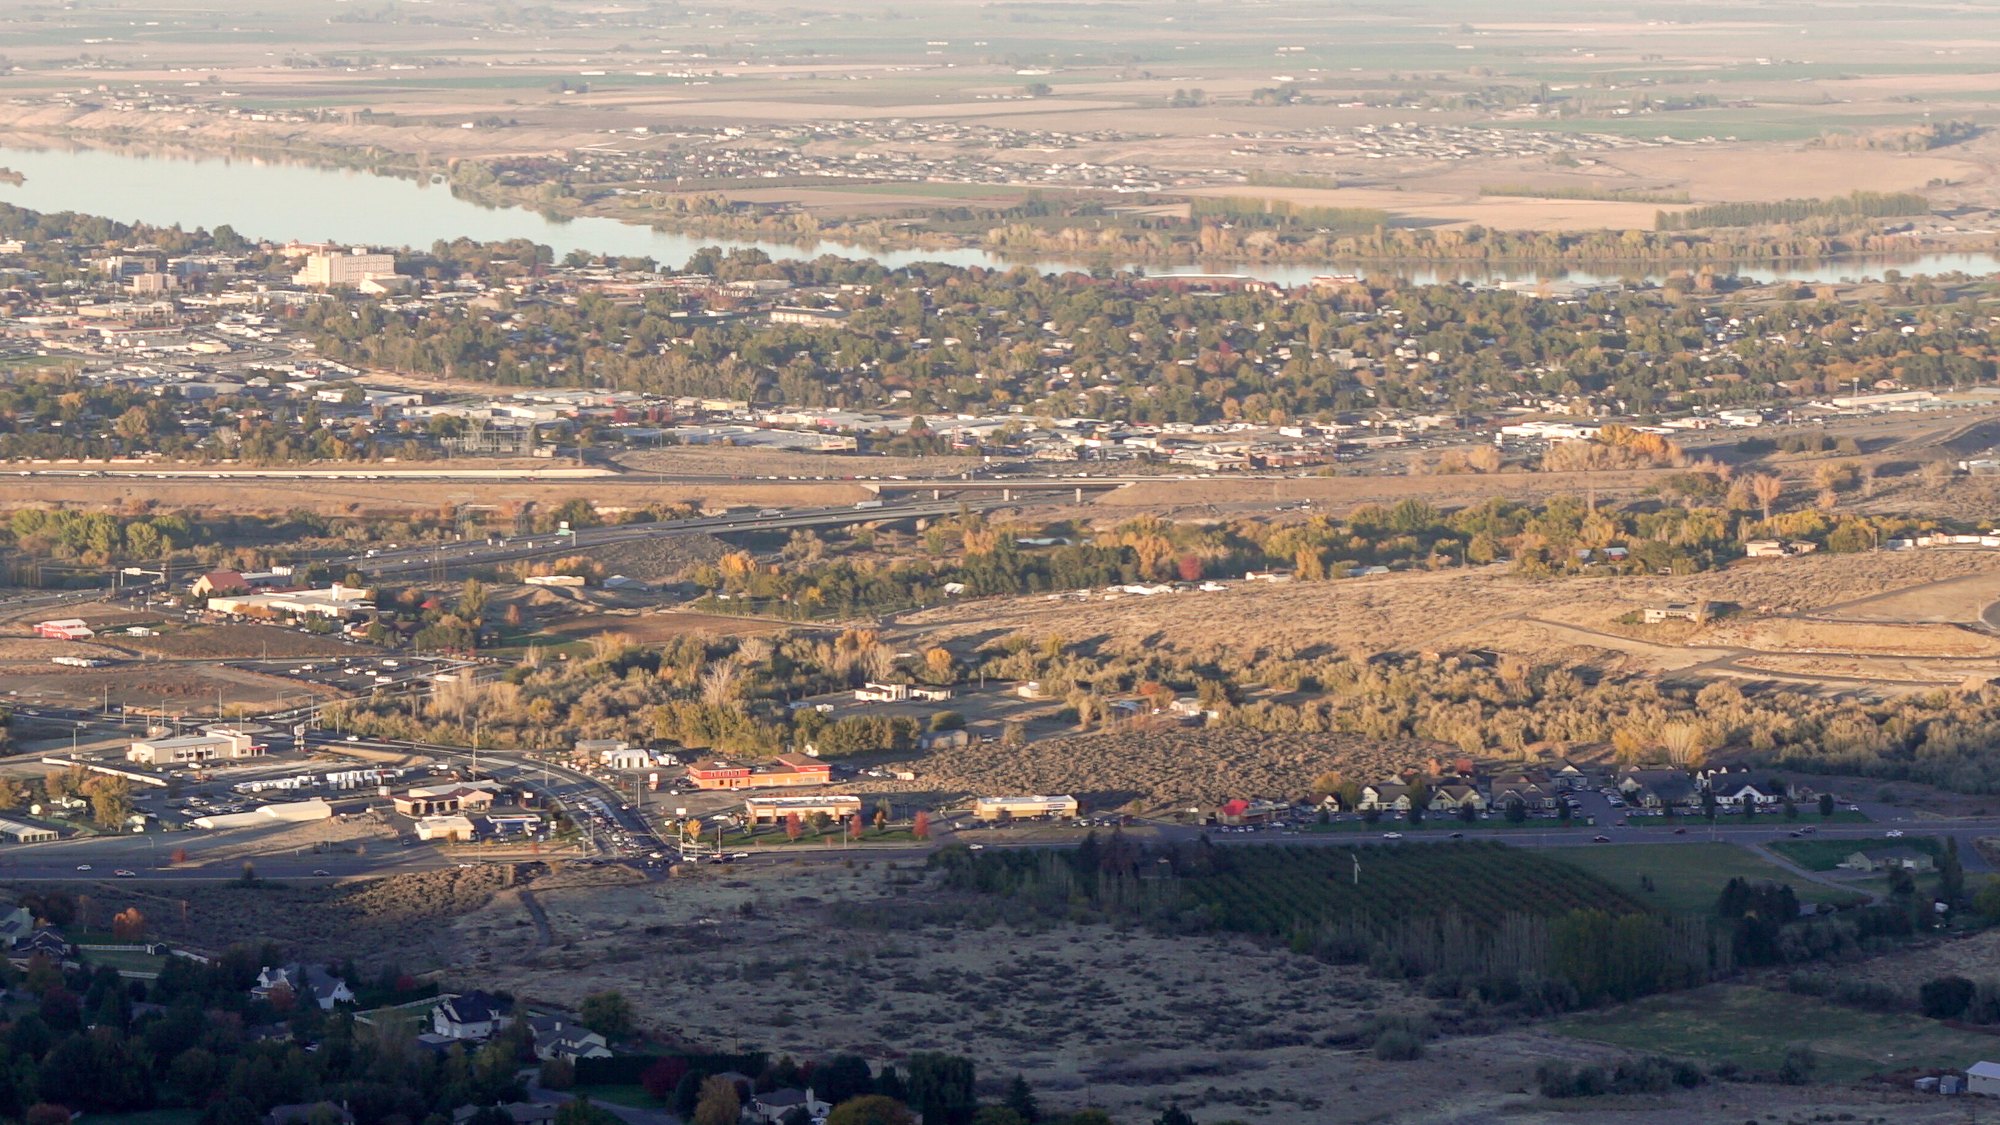
Kennewick, Pasco, Richland, and West Richland sit close together along the Columbia, Yakima, and Snake. A VA loan can be used in any of them when the home and the buyer meet the guidelines. The better question is which area fits your commute, budget, and daily life.
Home to the Richland VA Clinic in the Federal Building on Jadwin Avenue, close to Kadlec Regional Medical Center and many lab and Hanford-related jobs. Established neighborhoods, river paths at Howard Amon Park, and a mix of mid-century and newer homes.
The largest of the four cities, with shopping, restaurants, and a wide range of prices. A larger VA clinic is planned near Plaza Way in the Southridge area, with an expected opening in early 2029. Until then, many Veterans continue to use the Richland clinic.
A growing city with a lot of newer construction and, often, more house for the money. Easy access to Highway 395 and the airport. The Columbia Basin Veterans Center and county Veteran service resources are close by for claims help and local support.
A smaller city with many newer subdivisions, yards, and a quieter pace, still a short drive to Richland workplaces and the VA clinic. A good fit if you want space without leaving the metro.
The Jonathan M. Wainwright VA Medical Center in Walla Walla is about an hour’s drive and provides additional care in the region. We can help you weigh commute, schools, lot size, and whether a home is likely to meet VA property standards before you write an offer.
Maltos Realty Group
Justin and Ananda Maltos lead Maltos Realty Group, a Tri-Cities team brokered by Real Broker, LLC. We work with first-time VA buyers, families transferring here, and Veterans who already own a home and are ready to sell or buy the next one.
In a free buyer consultation we can talk through your timeline, whether you have your COE, what price range feels realistic, and which cities are worth a closer look. If you are selling, we can map a plan that respects your next move, including a VA purchase on the other side.
Request the guide below and we will email you a VA Home Buyer Guide with loan steps, a COE checklist, a simple timeline, and our contact information. You can also book a 30-minute call or reach Justin directly.
Call or text (509) 792-3977 or email justinmrealtor@gmail.com.
Get pre-approved
A pre-approval from a VA-experienced lender can strengthen your offer. Here are two lenders our buyers can choose to work with.
Sales Manager, loanDepot
US Navy Veteran
NMLS #2161015
(425) 367-8327
loanDepot.com, LLC, NMLS #174457. Equal Housing Lender.
Premier Loan Officer, Zillow Home Loans
NMLS #1617031
(206) 499-2021
Zillow Home Loans, LLC, NMLS #10287. Equal Housing Lender.
Maltos Realty Group is not a lender and is not affiliated with loanDepot or Zillow Home Loans. You may choose any lender, and your choice will not affect our service to you. We do not receive a fee for these introductions. Loan approval, rates, fees, and terms are set by the lender you choose. Verify a loan officer's license at nmlsconsumeraccess.org.
Free VA Home Buyer Guide
Answer a few questions and we will email you the guide. You can also request a free buyer consultation with Justin Maltos. There is no cost and no obligation.
Prefer to talk now? Call or text (509) 792-3977.
We will email your VA Home Buyer Guide shortly. If you asked for a consultation, Justin or a teammate will follow up to find a time that works.
You can also book a free 30-minute call now.
Book your free 30-minute consultationIf the guide does not arrive in a few minutes, check spam or call us at (509) 792-3977.